When a listing generates multiple bids, knowing how to handle competing offers financing types is one of the most valuable skills an agent can develop. Each financing method, whether cash, conventional, FHA, or VA, carries distinct timelines, contingencies, and risk profiles that directly affect the seller’s bottom line. In this guide, we break down every major loan type, explore the real differences that matter during negotiations, and share best practices for presenting offers so your clients can make confident, well-informed decisions.
Why Financing Type Matters in a Multiple-Offer Situation
Not all offers are created equal, even when the purchase price is identical. Two buyers can submit the same dollar amount, yet one offer might close in two weeks with minimal risk while another could take 45 days and carry appraisal contingencies that threaten the deal. Understanding why financing type matters is the first step toward advising your seller accurately.
The financing method a buyer uses influences several critical factors:
- Closing timeline – Cash deals can close in as few as 7 to 14 days, while government-backed loans may take 30 to 50 days.
- Appraisal requirements – FHA and VA loans have specific appraisal standards that can introduce repair demands or valuation disputes.
- Contingencies and fallthrough risk – Loans with stricter underwriting guidelines carry a higher chance of last-minute denial.
- Seller concessions – Some loan types allow buyers to request larger concession amounts, which affects the seller’s net proceeds.
- Property condition requirements – Government-backed programs enforce minimum property standards that conventional and cash offers do not.
According to the National Association of Realtors’ Profile of Home Buyers and Sellers, roughly 26 percent of recent home purchases were all-cash transactions. The rest relied on some form of mortgage financing, making it essential for listing agents to understand every loan type they might encounter.
Cash Offers: Strengths and Considerations
Cash offers are often viewed as the gold standard in competitive bidding. Without a lender involved, there is no loan approval process, no appraisal contingency tied to financing, and no risk of underwriting denial. But cash offers are not automatically the best choice for every seller.
Advantages of Cash Offers
- Speed – Closings can happen within one to two weeks since there is no lender timeline.
- Certainty – No financing contingency means the deal is far less likely to fall apart.
- Simplified process – Fewer parties involved results in less paperwork and fewer potential delays.
- No appraisal requirement – The buyer can choose to skip an appraisal, eliminating a common deal-killer.
Potential Drawbacks
- Lower offer price – Cash buyers often submit below asking price, expecting their certainty and speed to justify a discount.
- Proof of funds verification – Agents should always request and verify proof of funds to ensure the buyer actually has liquid capital available.
- Investor intentions – Some sellers prefer owner-occupant buyers over investors, especially in tight-knit communities.
Conventional Loan Offers: The Reliable Middle Ground
Conventional loans are mortgage products not backed by a government agency. They are offered through private lenders, banks, and credit unions and typically conform to guidelines set by Fannie Mae or Freddie Mac. For listing agents navigating competing offers financing types, conventional loans represent a strong middle ground between cash and government-backed options.
Why Sellers Often Prefer Conventional Offers
- Fewer property condition requirements – Unlike FHA and VA, conventional loans do not mandate specific health and safety repairs as a condition of financing.
- Flexible appraisal standards – While an appraisal is still required, conventional appraisals are generally less strict than government-backed ones.
- Faster closing potential – Conventional loans can close in 21 to 30 days with a well-prepared buyer.
- Lower concession limits – With a 20 percent down payment, seller concessions are capped at 9 percent of the sale price, but most conventional buyers ask for less.
Risk Factors to Watch
- Buyer qualification – Always verify the pre-approval letter. A pre-qualification is not the same as a full underwriting approval.
- Down payment amount – A buyer putting down 20 percent or more signals financial strength and eliminates private mortgage insurance, which strengthens the file.
- Loan-to-value ratio – Higher LTV ratios may face stricter underwriting, increasing fallthrough risk.
The Fannie Mae guidelines set the standard for most conventional loans in the United States. Agents should familiarize themselves with these guidelines to better evaluate the strength of a conventional offer.
FHA Loan Offers: What Listing Agents Need to Know
FHA loans are insured by the Federal Housing Administration and are designed to help first-time and lower-income buyers achieve homeownership. While these loans serve an important purpose in expanding housing access, they do come with specific requirements that listing agents should understand when evaluating competing bids.
Key Characteristics of FHA Offers
- Minimum Property Standards (MPS) – FHA appraisals evaluate both market value and property condition. Issues like peeling paint in pre-1978 homes, broken windows, faulty electrical systems, or roof deficiencies can trigger mandatory repairs before closing.
- Higher seller concession limits – FHA allows sellers to contribute up to 6 percent of the sale price toward closing costs, which buyers frequently request.
- Lower down payment – Buyers can put as little as 3.5 percent down, which means they have less skin in the game if values shift.
- Longer closing timelines – FHA loans typically take 30 to 45 days to close, and required repairs can extend this further.
Common Seller Concerns
Many sellers worry about FHA offers because of the appraisal requirements. If the FHA appraiser identifies health and safety issues, the seller may be required to make repairs before the loan can close. This creates additional cost and timeline uncertainty.
However, it is important to note that not all FHA appraisals result in repair requests. Properties in good condition often sail through the FHA appraisal process without issues. Agents should avoid blanket advice to reject FHA offers and instead evaluate each situation on its merits.
VA Loan Offers: Serving Those Who Served
VA loans are guaranteed by the U.S. Department of Veterans Affairs and are available to eligible service members, veterans, and surviving spouses. These loans offer exceptional terms for buyers, including zero down payment and no private mortgage insurance. For agents handling competing offers financing types, VA loans deserve thoughtful consideration rather than automatic skepticism.
Strengths of VA Offers
- Strong buyer qualification – VA underwriting is thorough. Buyers who receive a VA loan approval have typically passed rigorous income and credit verification.
- No down payment risk – While zero down payment might seem risky, VA loans historically have lower default rates than conventional and FHA loans, according to data from the U.S. Department of Veterans Affairs.
- Competitive interest rates – VA rates are often lower than conventional rates, which can improve buyer qualification.
Considerations for Sellers
- VA appraisal and Minimum Property Requirements – Similar to FHA, VA appraisals include property condition assessments. The VA has its own set of Minimum Property Requirements that must be met.
- Non-allowable fees – VA buyers are restricted from paying certain closing costs, which may shift those expenses to the seller depending on local custom.
- Closing timeline – VA loans typically close in 30 to 45 days, comparable to FHA timelines.
- Tidewater and Reconsideration of Value – If the VA appraisal comes in low, there is a formal process for challenging the value, which can add time but also provides a resolution path.
Side-by-Side Comparison of All Four Financing Types
When you are sitting at the kitchen table with your seller reviewing four different offers, it helps to have a clear mental framework. Here is how cash, conventional, FHA, and VA offers typically compare across the factors that matter most to sellers.
Closing Timeline
- Cash: 7 to 14 days
- Conventional: 21 to 30 days
- FHA: 30 to 45 days
- VA: 30 to 45 days
Appraisal Strictness
- Cash: No appraisal required (buyer’s choice)
- Conventional: Standard market value appraisal
- FHA: Market value plus Minimum Property Standards review
- VA: Market value plus Minimum Property Requirements review
Fallthrough Risk
- Cash: Very low (verify proof of funds)
- Conventional: Low to moderate (depends on buyer qualification strength)
- FHA: Moderate (appraisal and underwriting standards can create hurdles)
- VA: Low to moderate (thorough underwriting offsets some risk)
Typical Seller Concession Limits
- Cash: Negotiable, no formal limit
- Conventional: 3 to 9 percent depending on down payment
- FHA: Up to 6 percent
- VA: Up to 4 percent
This framework helps agents present a balanced view when discussing competing offers financing types with their clients. The goal is not to rank loan types in a rigid hierarchy but to weigh each offer’s full picture.
How to Present Competing Offers Fairly and Efficiently
As a listing agent, your fiduciary duty requires you to present all offers to your seller promptly and without bias. When multiple offers use different financing types, clear and organized presentation becomes even more important.
Organize Offers for Easy Comparison
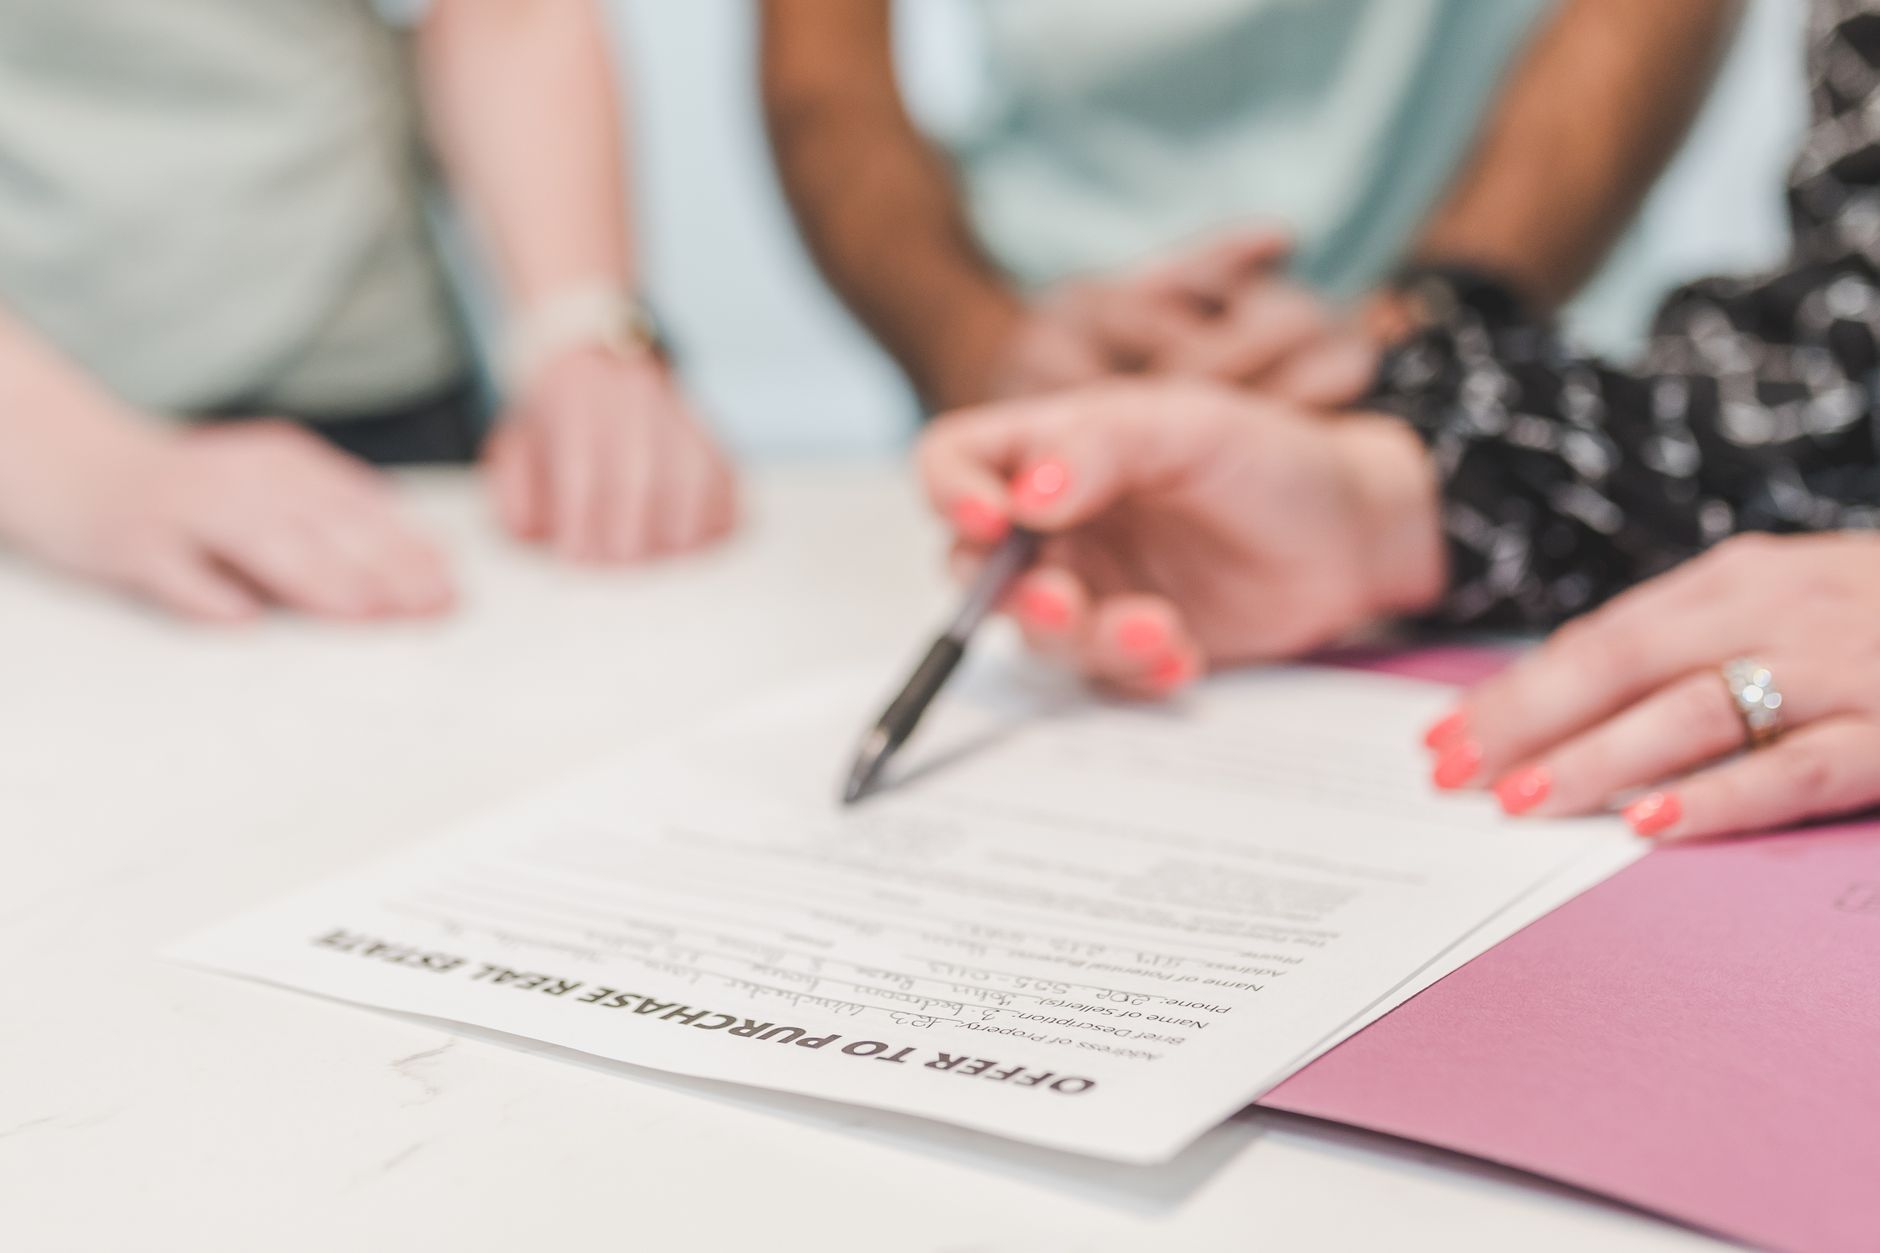
Create a standardized summary for each offer that highlights the key terms at a glance. Include the purchase price, financing type, down payment percentage, earnest money deposit, contingencies, requested concessions, proposed closing date, and any special terms or conditions. This allows your seller to compare apples to apples rather than reading through multiple contracts trying to spot differences.
A streamlined offer management platform can make this process significantly easier. Instead of manually creating spreadsheets or shuffling through stacks of paper, digital tools let you organize, compare, and present offers in a clean, professional format that helps sellers focus on the details that matter.
Present Net Proceeds, Not Just Price
The headline offer price does not tell the whole story. A $350,000 cash offer with no concessions might net the seller more than a $360,000 FHA offer requesting 4 percent in closing cost assistance. Always calculate the estimated net proceeds for each offer so your seller can see the true financial comparison.
Explain Risks Without Creating Bias
It is your job to educate, not to steer. Explain the realistic risks associated with each financing type while being careful not to dismiss government-backed offers unfairly. Present factual information about timelines, appraisal requirements, and contingencies, then let your seller decide based on their own priorities.
Best Practices for Managing Multiple Offer Scenarios
Handling multiple offers goes beyond just comparing financing types. The way you manage the process reflects your professionalism and can significantly impact the outcome for your seller.
Set Clear Expectations Early
Before the first showing, discuss your multiple-offer strategy with your seller. Decide in advance whether you will set offer deadlines, accept offers as they come in, or use a highest-and-best process. Having this conversation upfront prevents confusion when the offers start rolling in.
Communicate Transparently with Buyer Agents
When you receive multiple offers, notify all buyer agents that a multiple-offer situation exists. You do not need to disclose the number of offers or their terms, but transparency about the competitive environment gives buyers a fair chance to put their best foot forward. The NAR Code of Ethics provides guidance on proper disclosure in these situations.
Use Technology to Stay Organized
Multiple offer scenarios generate a flood of documents, emails, and phone calls. Staying organized is not optional. Digital tools that centralize offer documents, track communication timelines, and create audit trails are essential for compliance and efficiency.
For agents managing the full listing lifecycle, from open houses to offer review, integrated platforms can streamline the entire workflow. Capturing leads at the open house with a tool like EntryPointPro creates a pipeline that flows naturally into the offer review stage. And when you close the deal, maintaining professional relationships through a digital business card solution ensures that buyers who did not win this time remember you for the next opportunity.
Protect Your Seller’s Interests and Your License
Always follow your state’s real estate commission guidelines for handling multiple offers. Some states have specific rules about disclosure, documentation, and fair treatment. When in doubt, consult your broker or legal counsel. Proper handling of competing bids protects your seller, your reputation, and your license.
Frequently Asked Questions
Should sellers always choose a cash offer over a financed offer?
Not necessarily. While cash offers provide speed and certainty, a financed offer at a significantly higher price may result in greater net proceeds for the seller. It is important to evaluate the complete terms of each offer, including price, concessions, contingencies, and the buyer’s financial strength, rather than defaulting to cash simply because it eliminates lender involvement.
Can a seller legally reject an offer because it uses FHA or VA financing?
Technically, sellers can choose any offer for any business reason, and financing type is not a protected class under federal fair housing law. However, systematically rejecting government-backed loan offers could have disparate impact implications since FHA and VA programs disproportionately serve minority, lower-income, and veteran buyers. The safest approach is to evaluate every offer on its complete terms and document your reasoning.
How do appraisal differences between loan types affect the deal?
Cash buyers can waive appraisals entirely. Conventional appraisals focus on market value. FHA and VA appraisals assess both market value and property condition against specific minimum standards. If the property has deferred maintenance or health and safety issues, FHA and VA appraisals are more likely to require repairs before closing, which can add cost and time for the seller.
What is the best way to compare competing offers with different financing types?
Calculate the estimated net proceeds for each offer after accounting for concessions, closing costs, and any anticipated repair requirements. Then evaluate the certainty of closing by reviewing the buyer’s financial qualifications, the financing timeline, and the contingencies included in each offer. A side-by-side comparison that addresses both financial outcome and risk gives your seller the clearest picture.
How can technology help manage competing offers more efficiently?
Digital offer management platforms allow agents to organize, compare, and present multiple offers in a standardized format. These tools reduce the risk of errors, create documentation trails for compliance, and save significant time compared to manual processes. They also make it easier to communicate offer status updates to buyer agents, keeping the process transparent and professional.
Streamline Your Offer Management Process
Handling competing offers with different financing types is easier when you have the right tools. RLTRsync’s offer management platform helps you organize, compare, and present offers with clarity and confidence.
 Icon On The Top Right Is the Menu For Your Card. This Is Where You can edit your card and log into your dashboard.