Understanding contingency clauses is one of the most important skills a real estate agent can develop. These protective provisions shape the strength of every purchase offer, influence seller decisions, and directly impact how smoothly a transaction moves toward closing. Whether you are a newer agent building your knowledge base or an experienced professional brushing up on best practices, knowing how to explain, negotiate, and manage contingencies will set you apart in every listing presentation and offer review.
What Are Contingency Clauses in Real Estate?
A contingency clause is a condition written into a purchase agreement that must be satisfied before the transaction can proceed to closing. If the condition is not met within the specified timeframe, the buyer typically has the right to withdraw from the contract without forfeiting their earnest money deposit. In essence, contingencies serve as safety nets for buyers, but they also introduce uncertainty for sellers.
From the seller’s perspective, every contingency represents a potential exit point for the buyer. That is why listing agents must be able to clearly articulate the risks and implications of each contingency when presenting offers. A strong offer price can quickly lose its appeal if it comes loaded with contingencies that extend timelines or introduce deal-breaking conditions.
The most common contingency clauses you will encounter include inspection, financing, appraisal, home sale, and title contingencies. Some markets also see contingencies related to homeowners association (HOA) document review, insurance availability, and even well or septic inspections in rural areas. According to the National Association of Realtors, understanding these contract provisions is a core competency for all practicing agents.
The Inspection Contingency: Protecting Buyers from Hidden Issues
The inspection contingency is perhaps the most familiar and frequently used provision in residential real estate. It gives the buyer the right to hire a licensed home inspector to evaluate the property’s condition within a specified number of days after the contract is executed. If the inspection reveals significant defects, the buyer can request repairs, negotiate a credit, or walk away from the deal entirely.
For sellers, the inspection contingency can feel like a double-edged sword. On one hand, it is a standard and expected part of most transactions. On the other hand, it opens the door to renegotiation after the seller has already taken the property off the market. Buyers sometimes use inspection findings to request price reductions that go well beyond the cost of actual repairs.
What Listing Agents Should Watch For
- Inspection period length: Shorter inspection windows (7 to 10 days) are generally more favorable for sellers than extended periods of 14 days or more.
- Scope of inspection: Some contracts limit the inspection to major systems (roof, HVAC, foundation, plumbing, electrical), while others allow buyers to object to virtually any issue.
- As-is language: Offers with an “as-is” inspection contingency still allow buyers to walk away, but they signal the buyer does not intend to request repairs.
- Radon, mold, and pest inspections: These are sometimes included as separate contingencies or rolled into the general inspection clause.
When presenting an offer with an inspection contingency, help your seller understand the difference between a standard inspection period and one that gives the buyer excessive leverage. A well-structured inspection contingency protects the buyer without unfairly disadvantaging the seller.
Financing and Appraisal Contingencies Explained
The financing contingency, sometimes called a mortgage contingency or loan contingency, allows the buyer to back out of the contract if they are unable to secure mortgage approval within a specified timeframe. This is one of the most significant contingency clauses in any offer because it directly ties the deal’s success to a third party, the lender.
Understanding the Financing Contingency
When reviewing a financed offer with your seller, pay close attention to the following details:
- Pre-approval vs. pre-qualification: A pre-approval letter carries significantly more weight than a pre-qualification because it indicates the lender has already reviewed the buyer’s financials in detail.
- Loan type: Conventional, FHA, VA, and USDA loans each come with their own requirements. FHA and VA loans, for example, have stricter property condition standards that could trigger additional repair requests.
- Financing deadline: This is the date by which the buyer must obtain a firm loan commitment. Shorter deadlines typically indicate a more prepared buyer.
- Down payment amount: A larger down payment can reduce lender risk and improve the likelihood of loan approval.
The Appraisal Contingency
The appraisal contingency is closely related to financing but serves a distinct purpose. It allows the buyer to renegotiate or withdraw if the property does not appraise at or above the agreed-upon purchase price. Lenders require appraisals to ensure they are not lending more than the property is worth, so this contingency is standard in nearly all financed offers.
In competitive markets, buyers sometimes waive the appraisal contingency or include an appraisal gap clause, agreeing to cover the difference between the appraised value and the purchase price up to a specified amount. As a listing agent, understanding these nuances helps you guide your seller toward the strongest offer. The Consumer Financial Protection Bureau offers helpful resources for understanding how appraisals work in the lending process.
The Home Sale Contingency and Its Impact on Sellers
A home sale contingency makes the purchase of your seller’s property conditional on the buyer successfully selling their current home. This type of contingency can be particularly problematic for sellers because it introduces a dependency on a completely separate transaction that the seller has no control over.
There are two common variations of this contingency:
- Sale contingency: The buyer has not yet received an offer on their current home. This is the riskier version for sellers because the timeline is entirely uncertain.
- Settlement contingency: The buyer already has a buyer under contract for their current home and simply needs to close that transaction. This is generally less risky because the buyer’s sale is already in progress.
When presenting an offer with a home sale contingency, make sure your seller understands the practical implications. Their property may sit under contract for weeks or even months, potentially missing peak market activity, while waiting for the buyer’s home to sell. In competitive markets, sellers often reject or deprioritize offers with this contingency unless the offer price is substantially higher than competing offers.
The Kick-Out Clause
To protect sellers who accept offers with home sale contingencies, many agents include a kick-out clause (also known as a bump clause). This allows the seller to continue marketing the property. If another acceptable offer comes in, the original buyer is given a specified period, usually 48 to 72 hours, to either remove the home sale contingency and proceed with the purchase or release the seller from the contract.
Title and Insurance Contingencies You Cannot Overlook
The title contingency gives the buyer the right to review the title search results and object to any issues that could affect their ownership rights. Common title problems include outstanding liens, boundary disputes, easements, and errors in public records. While title issues are relatively rare in straightforward transactions, they can completely derail a deal when they do appear.
Most standard purchase agreements include a title contingency as a default provision, and it is generally in both parties’ best interests to keep it in place. A clean title protects the buyer’s investment and the seller’s liability. Title insurance, which is typically purchased at closing, provides an additional layer of protection against undiscovered defects.
Insurance Contingency Considerations
In some regions, particularly areas prone to flooding, wildfires, or hurricanes, an insurance contingency allows the buyer to withdraw if they cannot obtain homeowners insurance at a reasonable cost. This contingency has become increasingly relevant as climate-related risks have driven up insurance premiums in certain markets. According to HousingWire, rising insurance costs have become a significant factor in home purchasing decisions across multiple states.
As a listing agent, be prepared to discuss insurance availability proactively. If your seller’s property is in a high-risk area, having documentation about current insurance coverage and costs can help reassure prospective buyers and reduce the likelihood of deals falling through over insurance concerns.
How to Present Contingency-Heavy Offers to Sellers
Presenting offers effectively is an art that combines market knowledge, communication skills, and organizational clarity. When an offer includes multiple contingency clauses, it is especially important to present the information in a structured, easy-to-understand format so your seller can make an informed decision.
Build a Side-by-Side Comparison
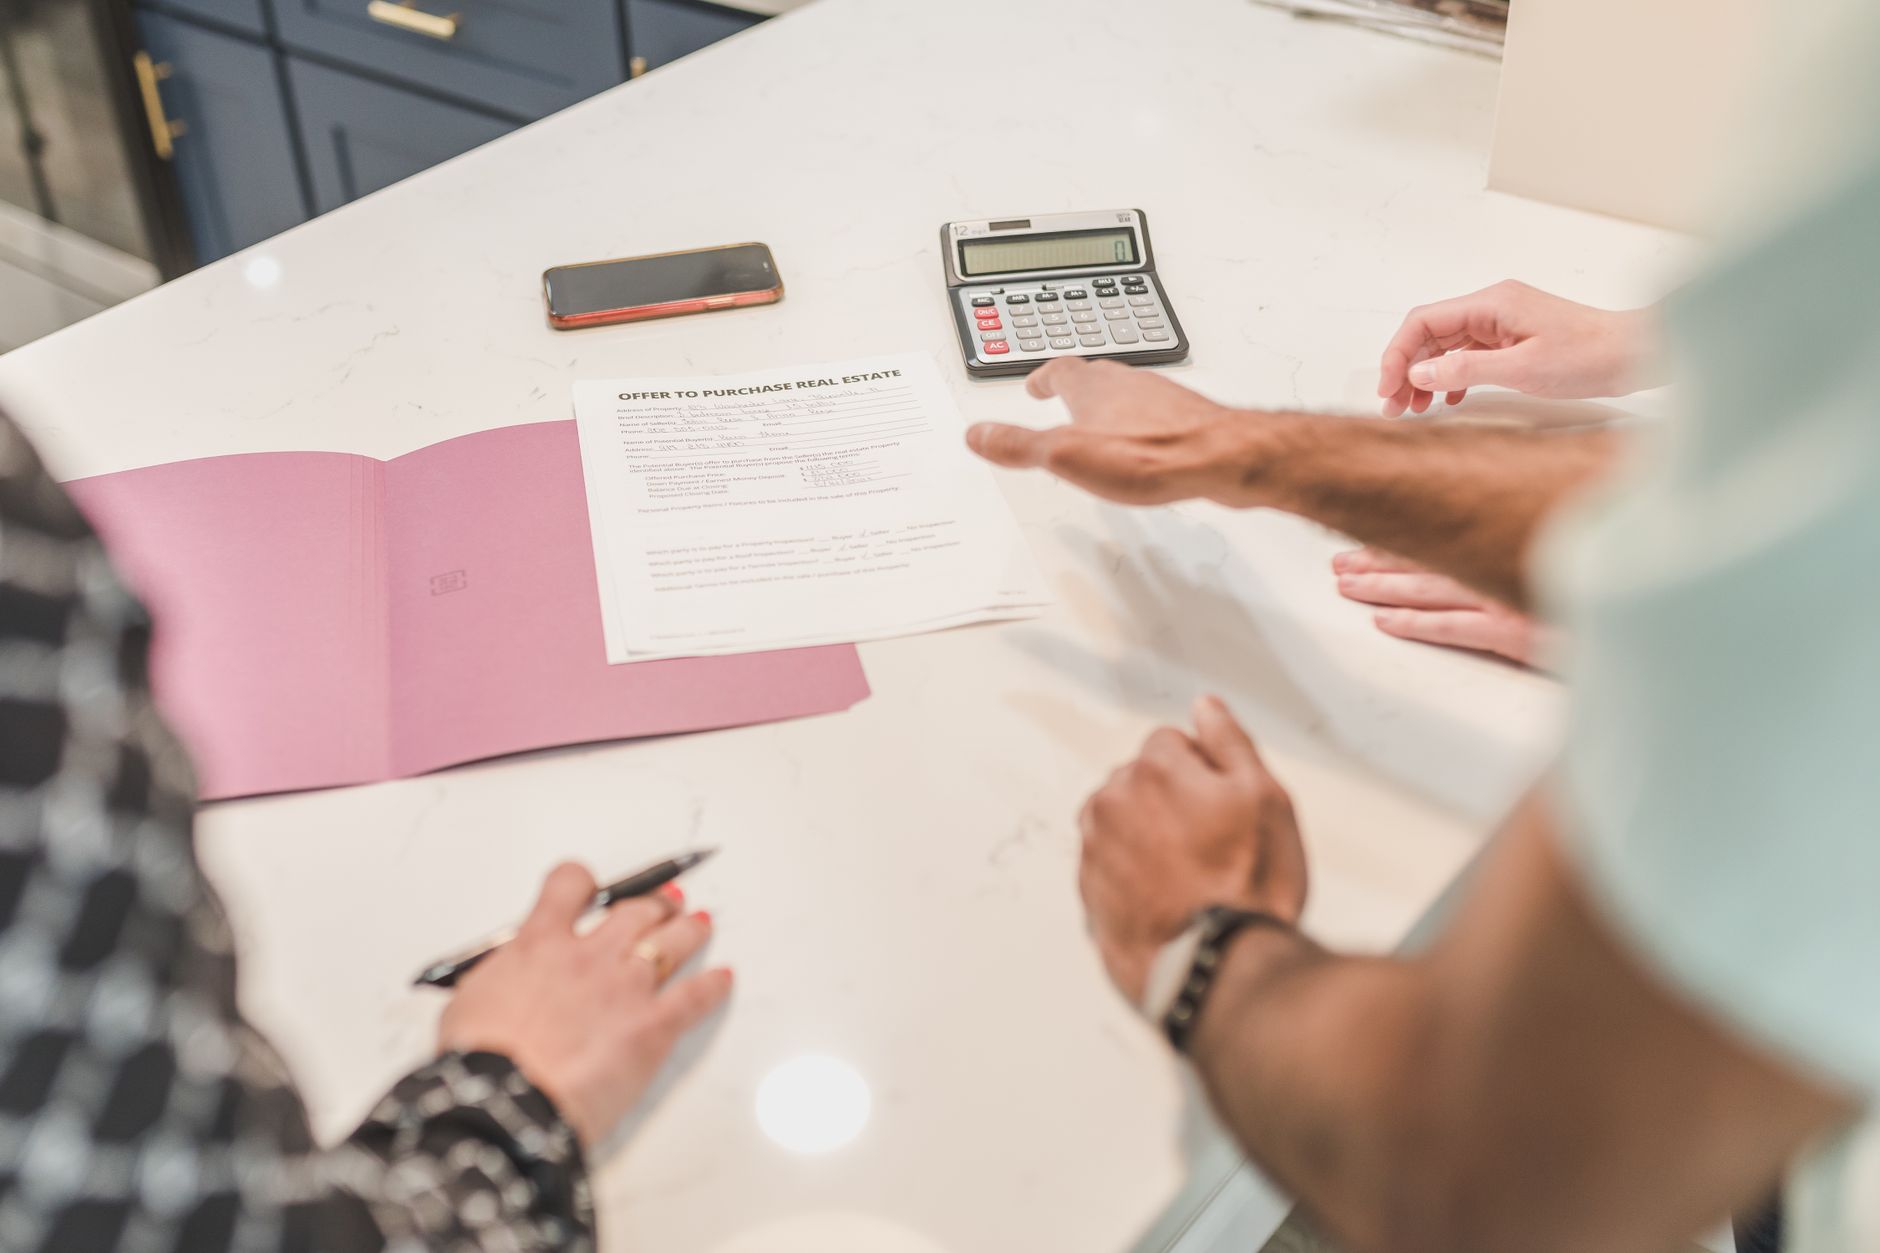
When multiple offers come in, creating a side-by-side comparison that highlights the key terms, including price, contingencies, timelines, and buyer qualifications, helps sellers quickly identify the strongest offers. Tools like RLTRsync’s Offer Management platform can streamline this process by organizing all incoming offers into a clear, professional format that makes comparison effortless.
Explain Risk vs. Reward
Help your seller understand that contingencies are not inherently bad. They are a normal part of real estate transactions. The key is evaluating the risk each contingency introduces relative to the overall strength of the offer. A slightly lower offer with fewer contingencies and a faster closing timeline might be more attractive than a higher offer loaded with conditions that could delay or derail the sale.
Use Clear, Non-Technical Language
Not every seller will understand terms like “appraisal gap coverage” or “kick-out clause” without explanation. Take the time to define each contingency in plain language and walk through realistic scenarios. What happens if the inspection reveals a major issue? What if the appraisal comes in low? What if the buyer’s home does not sell? Anticipating these questions builds trust and positions you as a knowledgeable advisor.
Strategies for Negotiating Contingency Removal
Skilled agents know that contingencies are often negotiable. In competitive markets, buyers may voluntarily waive or shorten contingency periods to make their offers more appealing. In balanced or buyer-friendly markets, sellers may need to accept more contingencies to attract qualified buyers. Here are several strategies for navigating these negotiations effectively.
Shortening Contingency Timelines
Rather than asking a buyer to remove a contingency entirely, consider negotiating shorter timelines. For example, reducing an inspection period from 14 days to 7 days or shortening a financing contingency from 30 days to 21 days can significantly reduce the seller’s risk without eliminating the buyer’s protections altogether.
Limiting Contingency Scope
Another approach is to narrow the scope of a contingency. For instance, an inspection contingency might be limited to major structural and mechanical systems only, excluding cosmetic issues. This gives the buyer meaningful protection while preventing trivial objections from becoming negotiation points.
Offering Incentives for Contingency Waivers
In some situations, sellers can incentivize buyers to waive certain contingencies. For example, a seller might offer a home warranty or a small price concession in exchange for the buyer waiving the inspection contingency. These trade-offs can help both parties reach a mutually beneficial agreement.
Escalation Clauses and Contingency Interactions
Escalation clauses, which automatically increase a buyer’s offer to outbid competitors up to a maximum price, can interact with contingencies in complex ways. For instance, an escalation clause that pushes the price above the appraised value could trigger the appraisal contingency. Make sure you and your seller understand how these provisions work together before accepting or countering an offer.
Maintaining organized records of all offers, counteroffers, and contingency modifications is essential during negotiations. Using a platform like RLTRsync’s Offer Management system ensures that nothing falls through the cracks and that all documentation is accessible when you need it.
Staying Compliant and Professional
Throughout the contingency negotiation process, it is critical to stay within ethical and legal boundaries. Agents should never pressure buyers to waive contingencies without understanding the risks, and listing agents must present all offers fairly and completely to their sellers. Your state’s real estate commission provides specific guidelines on offer presentation requirements, and the NAR Code of Ethics sets clear standards for professional conduct in these situations.
Beyond offer negotiations, agents who use digital tools for lead capture and client management can build stronger relationships from the very first interaction. For example, EntryPointPro helps agents capture and organize leads at open houses, creating a pipeline of potential buyers who may eventually submit offers on your listings. And when networking with fellow agents, having a polished RealConnect digital business card ensures you are always ready to make a professional impression.
Frequently Asked Questions
What are the most common contingency clauses in a real estate offer?
The most common contingency clauses include the inspection contingency, financing (mortgage) contingency, appraisal contingency, home sale contingency, and title contingency. Depending on the property location and type, you may also encounter insurance contingencies, HOA document review contingencies, and well or septic inspection contingencies.
Can a seller reject an offer because it has too many contingencies?
Yes. Sellers have the right to accept, reject, or counter any offer for any reason, including the number or type of contingencies included. In competitive markets, sellers often favor offers with fewer contingencies because they represent less risk and a more predictable path to closing.
Is it legal for a buyer to waive all contingencies?
It is legal for buyers to waive contingencies, but it is not always advisable. Waiving contingencies removes important protections, such as the ability to walk away if an inspection reveals major problems or if the property does not appraise at the purchase price. Agents should always ensure buyers understand the risks before waiving any contingency.
What happens to earnest money if a contingency is not met?
If a contingency is not satisfied within the agreed-upon timeframe and the buyer properly exercises their right to terminate the contract, the earnest money deposit is typically returned to the buyer. However, if the buyer fails to follow the contract’s procedures for termination, the earnest money may be at risk. The specific rules vary by state and contract.
How should I explain contingency clauses to first-time sellers?
Use simple, relatable language. Explain that contingencies are like conditions the buyer sets before they fully commit to the purchase. Use specific examples, such as “if the inspection finds a major problem with the foundation, the buyer can ask for repairs or cancel the contract.” Walking through real scenarios helps sellers understand the practical impact of each clause.
Streamline Your Offer Presentations with RLTRsync
Managing multiple offers with varying contingency clauses does not have to be overwhelming. RLTRsync’s Offer Management platform helps you organize, compare, and present offers with clarity and professionalism.
 Icon On The Top Right Is the Menu For Your Card. This Is Where You can edit your card and log into your dashboard.